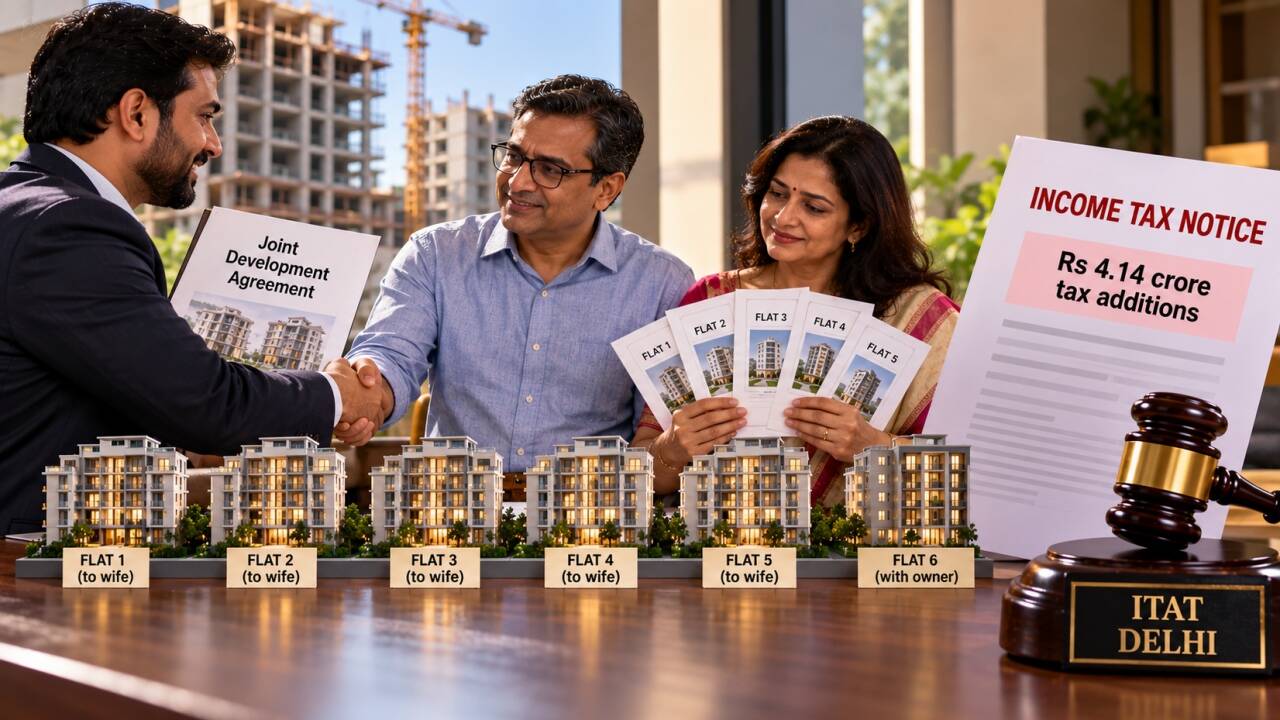
The assessing officer made two major additions in this case. The first, Rs 1,93,78,293, was treated as long-term capital gains on the ground that the man had converted a capital asset into stock-in-trade.
The second, of Rs 2,20,98,985, was treated as business income arising from the alleged sale of that stock-in-trade.
This story was reported by The Times of India. Read the full coverage at The Times of India.